 Start Your Retirement Roadmap
Protection · The What-If Question
Healthcare costs, Medicare, and long-term care can undo decades of good saving. Get ahead of them.
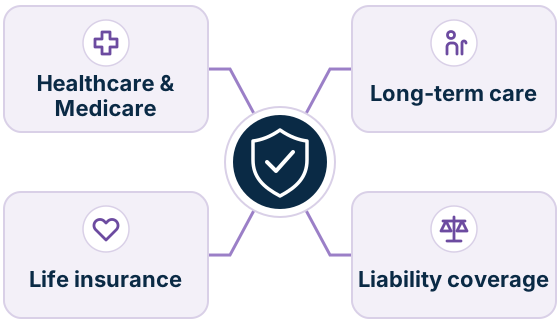
Protection planning is how you keep one bad event from undoing decades of careful saving: a health crisis, a long illness, a lawsuit, or an early death. It means checking your healthcare, Medicare, long-term care, life insurance, and liability coverage as one coordinated system instead of a drawer full of policies bought at different times for different reasons.
Most retirees have never had anyone review all of it together.
If you're within ten years of retirement, you've probably asked at least one of these:
Medicare doesn't cover everything, and long-term care is the single expense most likely to drain a portfolio that was otherwise on track.
Not more insurance. The right insurance. Many people carry a life policy sized for a mortgage they paid off years ago, and no coverage at all for the risks that actually matter now.
When one spouse dies, the household usually loses a Social Security check and sometimes a pension, while most of the bills stay the same. Survivor protection is a plan, not a hope.
Healthcare is one of the largest expenses in retirement, and costs continue to rise. That's not a reason to panic. It's a reason to plan.
Protection is one of the five planning areas, and it's the one that keeps a single bad event from undoing the rest. The work sorts into three moves: cover the health costs, protect your family, and shield your assets.
01 · HEALTH
Healthcare and long-term care are the two expenses most likely to derail a retirement.
02 · FAMILY
If something happens to you, the plan still has to hold for the people you love.
03 · ASSETS
One lawsuit or an uncovered loss can undo decades of saving. We find the gaps first.
A written plan that shows what you're protected against, what you're not, and exactly what to do about it, in plain English.
Where an annuity fits, we'll say so plainly and explain why. An annuity can provide a fixed income stream that the insurance company is contractually obligated to pay, which can take pressure off your portfolio in a down market. It's a tool, not a default. We only recommend one when it does a specific job in your plan.
Investment advisory services through Baynes Financial, LLC; insurance products through Baynes Financial and Insurance Services, LLC.
Book a Call
Protection Planning is one of the five planning areas of the Retire on Purpose Roadmap, alongside Income, Tax, Investment, and Legacy. And it touches every one of them. One coordinated plan means each area covers the others' blind spots.
This is for educational purposes only and not specific tax or legal advice. Consult your tax advisor and attorney.
FAQ
Mostly, no. Medicare covers short rehab stays after a hospital admission, but it doesn't pay for ongoing help with daily living, the kind of care most people actually end up needing. That's why long-term care gets its own line in your protection plan instead of a hopeful assumption.
Sometimes yes, sometimes no. It depends on whether anyone would be financially hurt if you died: a spouse losing a pension or Social Security check, a dependent, or an estate that would owe costs your accounts can't easily cover. We size the answer to the actual job, and if the honest answer is that you don't need it, we'll tell you that too.
An umbrella policy adds liability coverage on top of your home and auto policies, usually $1 million or more, and typically costs a few hundred dollars a year. If you've built meaningful assets, it's often the cheapest protection you can buy, because a single lawsuit can reach everything your other coverage doesn't.